ISLAMABAD: Pakistan has called for the immediate establishment of global regulatory and institutional frameworks to govern digital assets and shape the next generation of international finance.
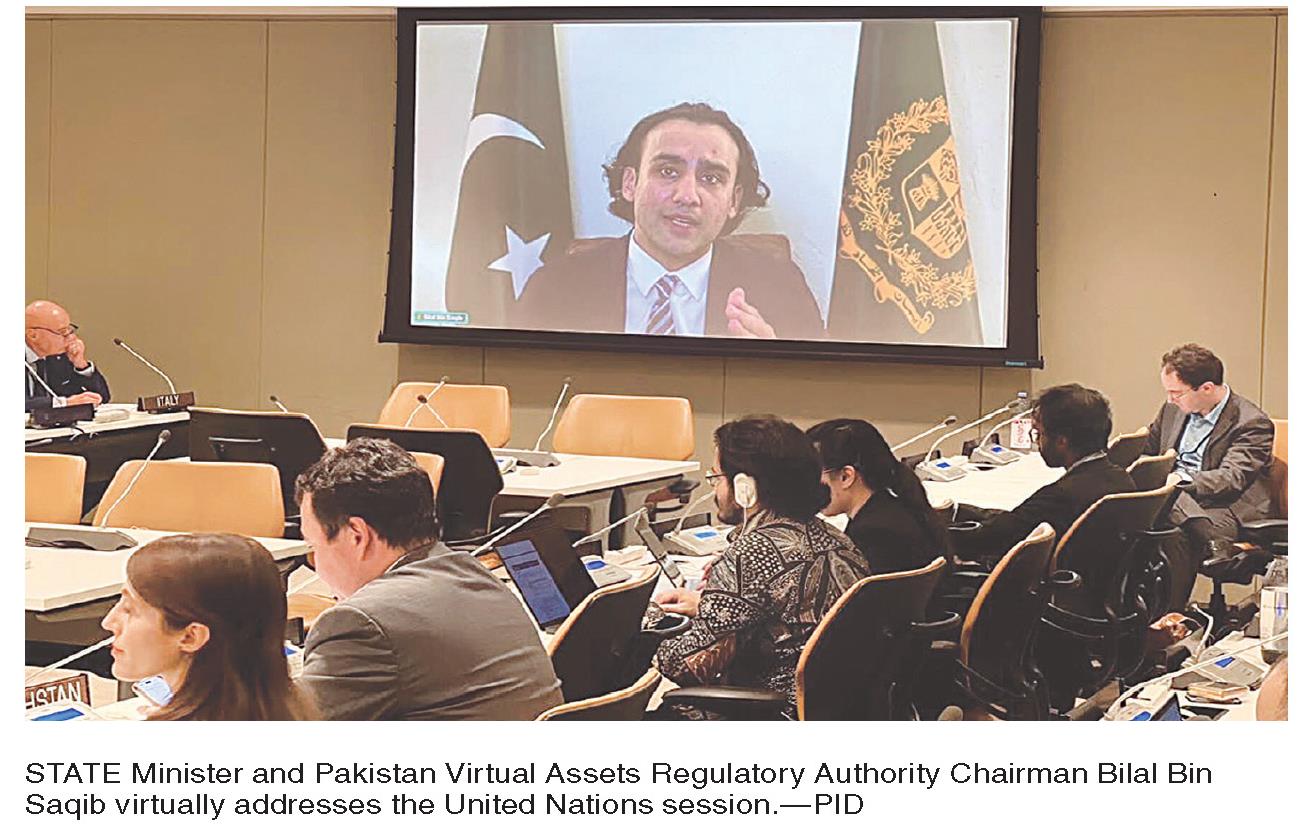
Speaking virtually at a United Nations briefing on Saturday, Minister of State and Pakistan Virtual Assets Regulatory Authority (PVARA) ChairmanBilalBin Saqiburged member states to build the institutional structures necessary to manage next-generation finance.
He noted that coordinated governance is essential toensure these financial innovations drive economic inclusion and efficiency.
Held at the United Nations headquarters, the session on ‘Digital Assets and Blockchain for Sustainable Development: Advancing Digital Finance through Innovation’ was convened by the Permanent Mission of Pakistan to the United Nations in collaboration with Undp, Unctad and the Office of the SecretaryGeneral’s Envoy on Technology, bringing together Member States, UN entities and privatesector stakeholders.
The PVARA chief stated digital assets, tokenisation and distributed ledger technologies present emerging economies with an opportunity to rethink financial infrastructure around inclusion, efficiency and access.
He emphasised that emerging technologies such as tokenisation and distributed ledgersoffer a critical opportunity to modernise global financial infrastructure and cooperation on global finance.
‘The question before this room is not whether these technologies will scale. They will.
The question is: who will shape them, and in whose interest?’ he asked.
Mr Saqib placed ordinary people at the centre of the debate, pointing to the 1.4 billion adults globally who remain outside the formal financial system, alongside billions more who participate on unequal terms through expensive remittances, slow settlement and limited access to credit.
The minister argued that digital finance’s development potential extends well beyond payments.
Digital identity and verifiable financial histories could help small businesses, farmers and women entrepreneurs demon-strate economic activity without relying exclusively on tr aditional collateral or documentation.
Meanwhile, tokenisation could create new ways to mobilise capital by fractionalising assets ranging from infrastructure bonds to renewable energy pr oje et s, while distribute d le dgers could strengthen transparency across public expenditure and supply chains.
These priorities closely align with the briefing’s broader focus on payments, remitt ances, financial inclusion, capital mobilisation, digital identity, traceability and responsible implementation.
However, Mr Saqib cautioned against treating technology as an automatic solution.
He highlighted risks ranging from retail volatility and illicit finance to the concentration of power and a widening divide between countries with sophisticated regulatory capabilitiesand those without.
‘The choice before every member state is not regulate or don’t regulate. It is simpler, and starker than that: to govern the future, or be governed by it.
He argued that regulation must evolve alongside innovation, warning that frameworks introduced too late can fail consumers and markets, while regulation driven primarily by fear can push technological activity into less transparent environments.
The emerging lesson from jurisdictions around the world, he said, is that regulation should be treated as marketbuilding rather than marketblocking.
‘No nation rises alone, and no nation should be left to rise alone.
He urged member states to use the briefing as the start of deeper cooperation rather than as an isolated discussion.